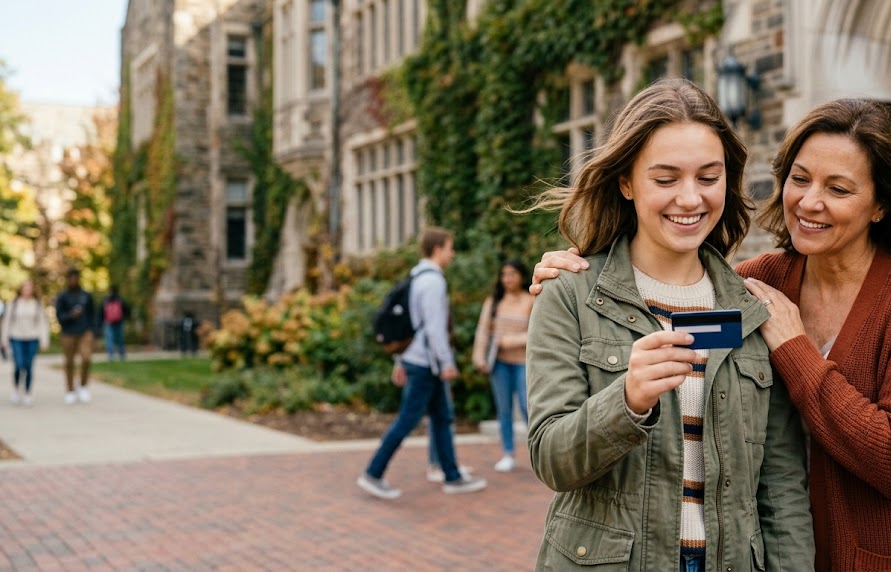
Adding someone to your plastic
You want to help a family member build credit, or maybe someone wants to help you. Adding an authorized user to a credit card lets a second person swipe with a card that has their name on it, but the primary account holder stays fully responsible for the bills. It is a popular way to jump-start a credit score without needing your own thick credit file first.
Before you mix finances with anyone, you want to make sure your own household budget is solid. Think of this like setting up your Banking & Savings so bills never bounce, or protecting your family with the right Insurance before taking on new risks. Good credit helps down the road when you apply for Mortgages or other Loans, but it is not a fix for a shaky monthly cash flow.
How spending limits work for users
When you add an authorized user, they usually share the exact same spending limit as the main cardholder. If your total limit is five thousand dollars, you and the other person both pull from that same pool. Some card issuers let you set a lower individual cap for the authorized user so they cannot run up the whole balance, but not all of them offer this feature.
Every purchase made on either card adds to the total balance. If that balance gets high, it hurts the credit scores of both people. Credit scoring models look at credit utilization, which is just the amount of debt you are carrying compared to your total limit. Keeping that utilization low is vital. If you plan to invest extra cash or apply for major financing soon, a maxed-out authorized user card can drag your numbers down fast.
What to compare and watch out for
Not all card companies report authorized user activity to the major credit bureaus in the same way. Before you add anyone, check if the issuer actually reports that user's history to all three bureaus. If they do not, the whole exercise is useless for building credit.
Look at whether the card has a cost. Many people stick to No annual fee cards for this exact reason so they are not paying extra just to share an account. If you travel a lot, you might look at Travel rewards cards, or prefer Cash-back cards for everyday groceries. Just remember that adding a user to Business cards works differently and often requires separate liability agreements.
The hidden costs and traps
The biggest trap is shared liability. Even if the authorized user promises to pay for their own purchases, the primary cardholder is legally on the hook for the entire bill. If the user misses a payment or runs up charges they cannot cover, your credit score takes the hit right alongside theirs.
You also need to watch out for the annual percentage rate (APR), which is the yearly cost of borrowing money when you carry a balance from month to month. If you pay your bill in full every single month, the APR does not matter. But if you carry a balance, that interest stacks up quickly. On the saving side, people sometimes confuse borrowing costs with the annual percentage yield (APY), which is the yearly interest earned on money sitting in a bank account. Keep those two straight so you know who is paying whom.
Setting clear rules
If you decide to add someone, sit down and set ground rules first. Decide who pays which bills, what purchases are allowed, and what happens if money gets tight. Trust helps, but clear boundaries keep friendships and family ties intact when money gets involved.