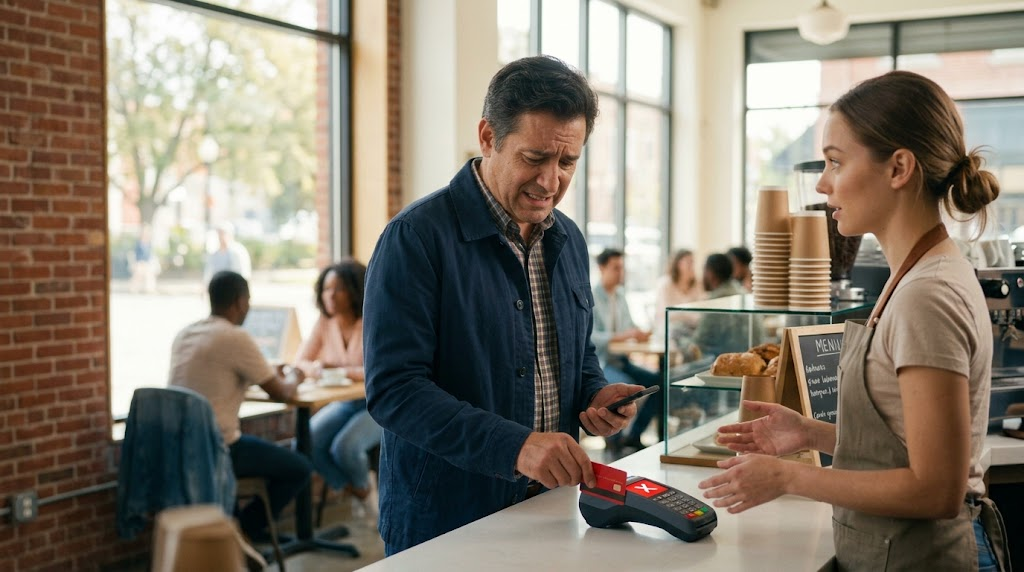
The Dreaded Decline
There is nothing quite like the silence of a card reader spitting back a decline while people wait behind you in line. It is awkward, but it happens to everyone. Usually, the issue is not that you are broke. It is just a quick safety check or a simple math error on your account. When you are working on your credit through cards for building credit, a decline can feel like a personal failure. Take a breath. It is almost always fixable in two minutes on your phone.
The Usual Suspects
Fraud alerts are the number one culprit. If you are buying something outside your normal routine, halfway across the country, or even just a larger amount than usual, the security system slams the brakes. It wants to make sure a thief is not draining your account. Another common block is hitting your limit. Your credit limit is the ceiling of what you can borrow. If you are close to it, one big tank of gas or a grocery run can push you over the edge.
Sometimes the details are just wrong. If you typed the wrong expiration date or security code on an online checkout, the system rejects it instantly. Expired physical cards also catch people off guard. Banks mail new ones every few years, and the old plastic stops working entirely.
How Costs and Interest Work
While a decline does not cost you money directly, what you do next might. If you were trying to buy something you could not actually afford, you risk carrying a balance. When you carry a balance from month to month, the card charges interest. That cost is measured by the annual percentage rate (APR), which is the yearly cost of borrowing money on your plastic, expressed as a percentage. Keep that number low by paying your bill in full every single month.
If you have money sitting in a separate account for your everyday cash, you might notice your savings grow a bit from interest. That return is often measured by the annual percentage yield (APY), which is the yearly rate of return you earn on deposited funds, including compound interest. Just remember that what your savings earns has no direct bearing on why a store rejects your plastic at the register.
Looking at the Bigger Financial Picture
Your credit card is just one gear in a much larger financial machine. What happens with your plastic touches other parts of your money life. For instance, lenders look closely at your overall credit habits when you apply for bigger things down the road, like car loans or even mortgages to buy a house. They want to see that you manage your plastic responsibly and rarely face sudden blocks or missed payments. If you eventually move on to more advanced products like travel rewards cards or cash-back cards, keeping an eye on your limits becomes even more important so you never hit a surprise wall.
Some people also manage everyday expenses through business cards if they run a side hustle, which keeps their personal spending separate. Regardless of the plastic in your wallet, keeping your accounts healthy helps protect your overall standing. Even if you prefer no annual fee cards to keep your costs at zero, the basic rules of spending limits and fraud alerts remain the same.
Long-term financial health also means looking beyond daily plastic. People often balance their card habits with long-term goals like investing for retirement or setting aside cash in reliable banking and savings accounts. And just like you protect your credit line, protecting your income and property with the right insurance policies ensures a surprise expense does not derail your whole budget.
The Catch to Watch For
The main trap with credit card limits is thinking they are extra money. They are not. They are temporary loans. Treat your plastic like cash, check your app before making a huge purchase away from home, and you will dodge most of these embarrassing declines before they happen.