0% intro APR for 15 months on purchases and b… Discover it® Cash Back Calculators How we make money
VOATLAS
How to Buy a Performance Brake Kit Without Wrecking

How to · Auto

How to Buy a Performance Brake Kit Without Wrecking

Upgrade your brakes during spring rebate events and spread the cost out without paying interest.

Typical cost $650 before anything else
Across the 0% window $36.11/mo 18 months, no interest

How we got that: $650 spread evenly across the 18-month introductory window on the Citi Simplicity® Credit Card. Checked · at the bank Carry a balance past the window and the standard APR applies to what is left.

There is nothing quite like the bite of fresh performance pads and rotors when you lean into a corner. Keeping a car running right means swallowing repair bills when parts wear out, and brakes are the one thing you cannot put off. Spring is the sweet spot for buying online because manufacturers drop their rebate events right as track season starts.

We need to talk about price separately from how you pay. Lock in your best price through online enthusiast forums or distributor sales before you even look at a payment window. A financing term is just a tool to smooth out the cash flow, not a discount on the hardware.

That 0% window is a hard deadline, not free money. If you still carry a balance when the 18 months are up, deferred interest or standard rates will kick in on what is left.

The steps

  1. 01

    Hunt for the spring rebate

    Check online performance shops and manufacturer sites during spring promotional windows. Look for mail-in rebates or bundle deals on pads and rotors together to shave real dollars off the typical $650 cost. Do this before you touch any financing.

  2. 02

    Line up your tools

    Make sure you have a torque wrench, a brake piston tool, and plenty of high-temp grease in your garage before the boxes arrive. Doing the labor yourself saves hundreds in shop fees, leaving room in your budget for the parts you actually want.

  3. 03

    Use your card term

    You can use the Citi Simplicity® Credit Card to get 0% for 18 months on purchases and balance transfers from date of account opening. That breaks the roughly $650 total down into about $36.11 per month if you spread it across the entire window.

  4. 04

    Set an auto-pay

    Divide your total by the months you have and set a recurring transfer so you do not have to think about it. Missing a payment is how people accidentally trigger steep interest charges.

  5. 05

    Bed in the pads

    Follow the manufacturer instructions for bedding in the new pads and rotors carefully. Skipping this step ruins the bite and leads to annoying squeal right out of the driveway.

  6. 06

    Check the card terms before you commit

    Every figure we publish for the Citi Simplicity® Credit Card carries the date a person verified it against Citi and a link to where they checked. Intro windows and APRs change without notice, so confirm the current terms before applying.

    See Citi Simplicity® Credit Card terms →

Common questions

Should I buy drilled or slotted rotors?

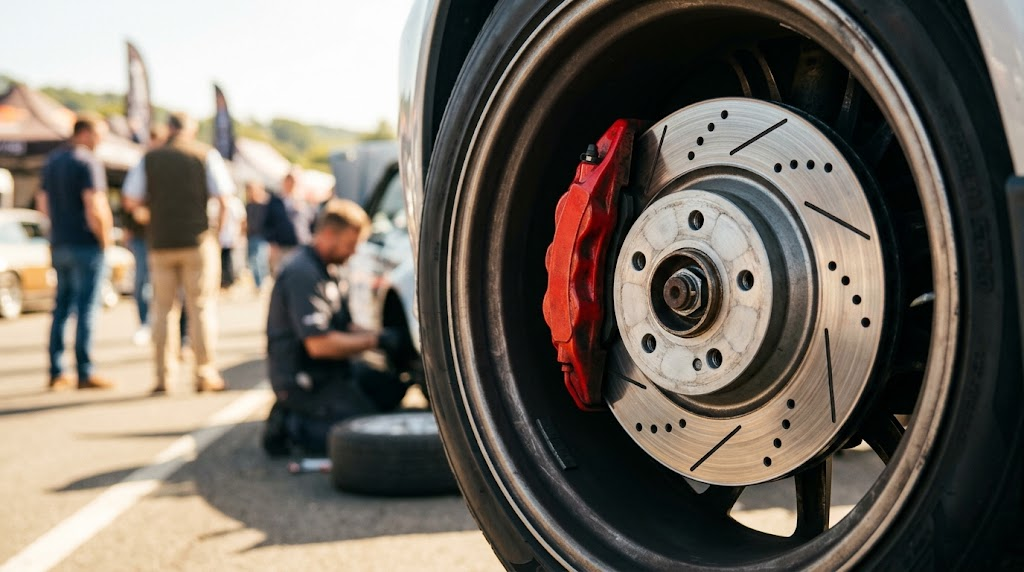
Slotted rotors handle heat and gas venting better under hard street and track driving without cracking like drilled ones sometimes do. Stick to blanks or simple slots unless you just really like how drilled ones look.

Do I really need new pads and rotors at the same time?

Usually, yes, because old rotors develop ridges and uneven wear that chew through fresh pads in no time. Changing both together ensures a clean, flat surface for proper stopping power.

What happens if I miss a monthly payment?

Missing a payment can break the promotional rate and trigger late fees. Keep that auto-pay locked in so you never miss the target.

Are performance pads too noisy for daily driving?

Some aggressive race compounds will squeal until they get warm, but most street-performance ceramic or semi-metallic pads are quiet enough for daily commuting. Read user reviews for the specific compound before you buy.