0% intro APR for 15 months on purchases and b… Quicksilver Rewards Calculators How we make money
VOATLAS
How to Buy Upgraded Brake Rotors Without Wrecking Your Cash

How to · Auto

How to Buy Upgraded Brake Rotors Without Wrecking Your Cash

A set of high-performance brake rotors costs about $500, and here is how to time the purchase and pay for them without sweating the bill.

Typical cost $500 before anything else
Across the 0% window $33.33/mo 15 months, no interest

How we got that: $500 spread evenly across the 15-month introductory window on the Discover it® Cash Back. Checked · at the bank Carry a balance past the window and the standard APR applies to what is left.

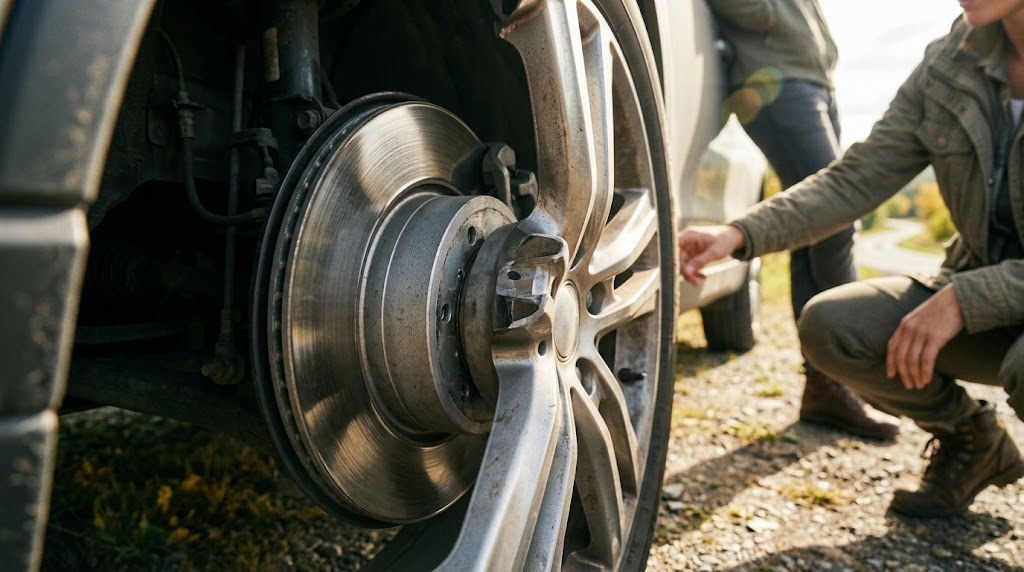
Upgraded high-performance brake rotors change how your car bites when you step on the pedal, especially if you deal with heavy stop-and-go traffic or mountain roads. Running a car is full of these inevitable maintenance hits, and parts wear out whether you are ready to pay for them or not. Prices on auto parts tend to dip around major holiday weekends in the fall and spring, so if your brakes are not grinding yet, waiting for a holiday sale can save you a chunk.

When you are staring down a $500 parts bill, separating the cost of the hardware from how you actually pay it off keeps things manageable. You want to negotiate the price of the rotors and any matching pads directly with the parts dealer or mechanic first before bringing any payment tool into the mix. Once you have the final out-the-door price, you can map out a steady payment plan that fits your monthly cash flow.

Keep in mind that the 0% intro APR for 15 months on purchases and balance transfers is a hard deadline, not free money. If you still have a remaining balance when those 15 months are up, interest will kick in on the original amount from day one.

The steps

  1. 01

    Check your current pad wear

    Measure your brake pad thickness before buying anything. If your current rotors are still smooth and within spec, you can wait for a holiday parts sale to buy the replacements.

  2. 02

    Shop around for parts bundles

    Look at online specialty auto shops for bundles that include both rotors and ceramic pads. Buying them together usually saves you money compared to grabbing them separately.

  3. 03

    Negotiate the labor rate

    If you are having a shop install them, ask for a breakdown of parts versus labor costs. Independent mechanics will often match online parts prices if you ask directly.

  4. 04

    Set up your payment window

    Using the Discover it® Cash Back card gives you a 0% intro APR for 15 months on purchases and balance transfers to spread out the $500 cost. Dividing that total evenly means paying about $33.33 per month to clear the balance before the intro period ends.

  5. 05

    Schedule the installation

    Book the install for right when your current pads start squealing. Getting it done proactively keeps you safe and prevents the rotors from scoring.

  6. 06

    Check the card terms before you commit

    Every figure we publish for the Discover it® Cash Back carries the date a person verified it against Discover and a link to where they checked. Intro windows and APRs change without notice, so confirm the current terms before applying.

    See Discover it® Cash Back terms →

Common questions

Are high-performance rotors really worth the extra money?

If you drive aggressively, tow loads, or live in a hilly area, slotted or drilled rotors manage heat much better than stock blanks. For normal daily commuting, standard blanks work fine and cost less.

Should I replace my brake pads at the same time?

Yes, always put new pads on new rotors. Old pads have uneven wear patterns that will score your expensive new rotors and ruin their performance quickly.

Can I install brake rotors myself?

If you have a jack, jack stands, and basic metric sockets, swapping rotors is a straightforward weekend job. If you lack the tools or garage space, let a local shop handle it.

What happens if I miss a monthly payment during the 15 months?

Missing a payment can trigger late fees and might cause the card issuer to cancel your promotional rate early. Set up automatic minimum payments so you never miss the due date.