0% for 12 months on purchases and 0% for 21 m… Citi® Diamond Preferred® Credit Card Calculators How we make money
VOATLAS
How to Pay for Front Brake Pads and Rotors

How to · Auto

How to Pay for Front Brake Pads and Rotors

A complete guide to timing your brake replacement, bundling services, and spreading out the cost without paying interest.

Typical cost $650 before anything else
Across the 0% window $43.33/mo 15 months, no interest

How we got that: $650 spread evenly across the 15-month introductory window on the Discover it® Cash Back. Checked · at the bank Carry a balance past the window and the standard APR applies to what is left.

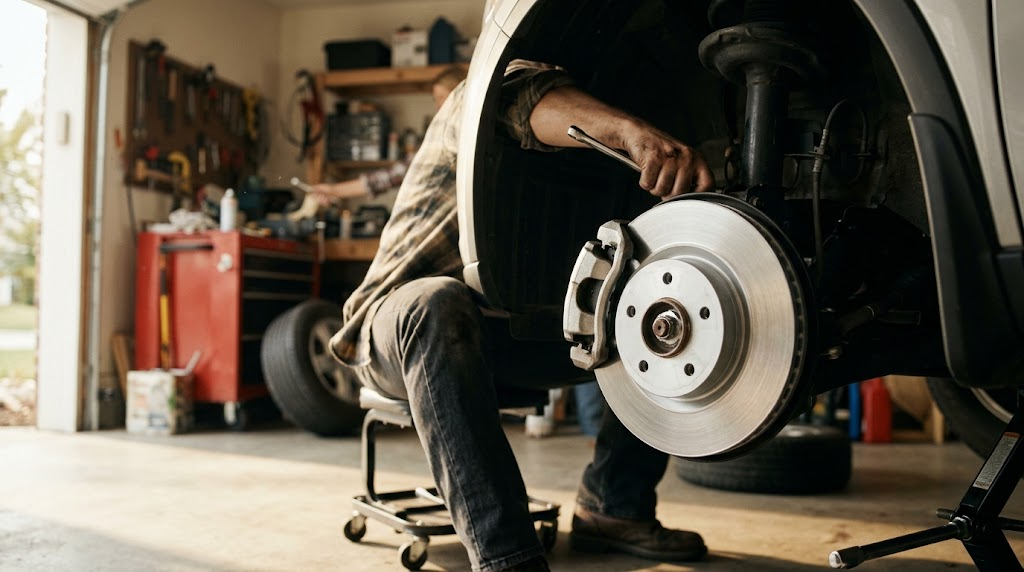
Worn brakes make that awful scraping sound right when you least want an extra bill. Keeping a car on the road means dealing with routine wear, and brakes are one of those things you simply cannot ignore. Spring shop specials are the best time to handle this because service centers drop their labor rates to fill bays.

Before you talk about how you are going to pay, get the shop to separate parts from labor on the estimate. You want to know what the pads and rotors actually cost by themselves. Once you have a firm number, we can look at the best way to handle the cash flow.

Remember that the 0% intro APR for 15 months on purchases and balance transfers is a hard deadline, not free money. If you still have a remaining balance when those 15 months run out, the card company will charge interest on the original amount from day one.

The steps

  1. 01

    Get multiple quotes

    Call at least two independent shops and one dealership to get separate estimates for pads and rotors. Ask if they charge a diagnostic fee to look at the car. Use the lowest quote to negotiate with the shop you actually want to use.

  2. 02

    Bundle with spring specials

    Book the brake job at the same time you schedule your seasonal tire rotation. Shops often waive part of the labor overlap since the wheels have to come off anyway. Spring promotional pricing usually undercuts the rush we see before winter weather hits.

  3. 03

    Use your card term

    Put the $650 bill on your Discover it® Cash Back to take advantage of the 0% intro APR for 15 months on purchases and balance transfers. This gives you breathing room to pay for the repair over time instead of draining your checking account today.

  4. 04

    Set up automatic payments

    Divide your total repair bill by your timeline to keep yourself on track. If you spread the $650 across the 15-month window, you are looking at $43.33 per month. Automate this exact amount so you never miss a beat.

  5. 05

    Confirm parts warranty

    Make sure the shop puts a warranty on both the pads and the rotors in writing. Cheap replacement parts can warp quickly and bring back that shudder when you stop. A decent shop will stand by their hardware for at least a year.

  6. 06

    Check the card terms before you commit

    Every figure we publish for the Discover it® Cash Back carries the date a person verified it against Discover and a link to where they checked. Intro windows and APRs change without notice, so confirm the current terms before applying.

    See Discover it® Cash Back terms →

Common questions

How do I know if I actually need new rotors?

If your steering wheel shakes when you brake, or if the pedal feels spongy, your rotors are likely warped or too thin. Shops will measure the thickness with a caliper to see if they can be resurfaced or if they need full replacement.

Should I buy the parts myself online?

Most shops will not install customer-provided parts because they cannot offer a labor warranty on them. If the parts fail, you end up paying for labor a second time. Let the shop source the hardware so they own the whole job.

Can I just replace the brake pads and skip the rotors?

You can only do a pad-only swap if your current rotors are above the minimum thickness limit and have no deep grooves. Most modern cars use thinner rotors that wear down alongside the pads, meaning a full replacement is safer and prevents squealing.

What happens if I miss a monthly payment during the intro period?

Missing a payment or paying less than the minimum can cause the card issuer to cancel your promotional rate early. Always pay at least the minimum due on time, even if you are aiming to pay off the $650 in chunks.