0% Intro APR for 15 months on purchases and b… Citi Strata℠ Card Calculators How we make money
VOATLAS
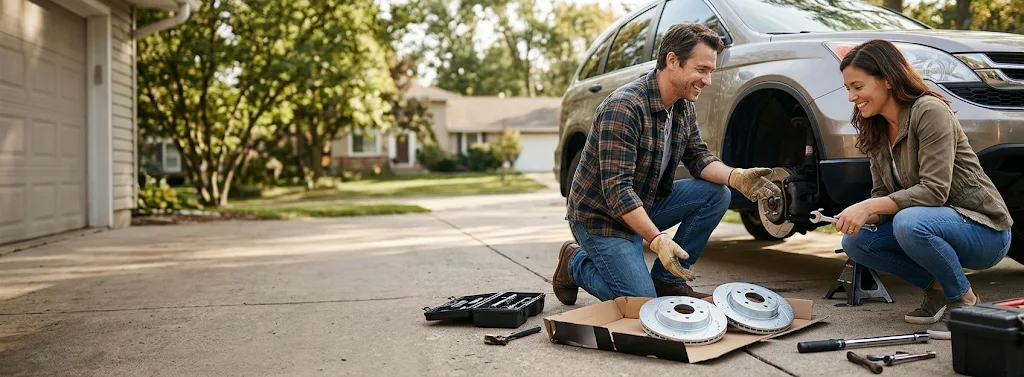
How to Pay for Performance Brake Rotors

How to · Auto

How to Pay for Performance Brake Rotors

A practical plan to upgrade your brakes without taking a single big hit to your bank account.

Typical cost $900 before anything else
Across the 0% window $50.00/mo 18 months, no interest

How we got that: $900 spread evenly across the 18-month introductory window on the Citi Simplicity® Credit Card. Checked · at the bank Carry a balance past the window and the standard APR applies to what is left.

Performance cars are great until maintenance bills land. Rotors and pads are a consumable tax on driving something fun, and dropping $900 all at once stings. Auto parts prices usually soften in late fall and winter during holiday promotions, which is the ideal time to stock up before your current pads wear down to metal.

Negotiating parts pricing happens separately from how you actually finance the job. You buy the hardware at a discount first, then use a tool like the Citi Simplicity® Credit Card to spread out the cost over time while keeping cash in your bank account.

Remember that an intro APR window is a strict deadline, not free money. If you do not clear the full $900 balance before the 18 months run out, the regular interest rate kicks in on whatever balance is left.

The steps

  1. 01

    Track pad wear early

    Inspect your brake pads every oil change so you are not caught off guard. When inner padding hits three millimeters, order your rotors before metal touches metal. Waiting too long turns a routine swap into an emergency buying situation.

  2. 02

    Shop seasonal sales

    Parts suppliers discount high-end brake packages during Black Friday and end-of-year clearance events. Look for complete kits that bundle rotors and matched pads to save on shipping. Call local shops to ask if they match online retailer pricing.

  3. 03

    Separate parts from labor

    Buy your rotors directly instead of letting a garage mark up the hardware costs by thirty percent. Negotiate a flat labor rate with an independent mechanic for the install. If you have the tools and garage space, doing the swap yourself costs zero extra dollars.

  4. 04

    Use an interest-free window

    Pay for the hardware using the Citi Simplicity® Credit Card, which offers 0% for 18 months on purchases and balance transfers from date of account opening. Breaking a $900 set of rotors into 18 monthly payments comes out to $50.00 per month. That gives you breathing room without adding interest to your build.

  5. 05

    Bed the new rotors

    Once installed, follow the manufacturer's bedding procedure to transfer pad material evenly across the drilled surface. Doing five to ten moderate stops from forty miles per hour prevents hot spots. Proper break-in extends the life of both your new pads and your hardware.

  6. 06

    Check the card terms before you commit

    Every figure we publish for the Citi Simplicity® Credit Card carries the date a person verified it against Citi and a link to where they checked. Intro windows and APRs change without notice, so confirm the current terms before applying.

    See Citi Simplicity® Credit Card terms →

Common questions

Are cross-drilled rotors worth the extra money?

They help vent heat and gas under hard driving, which reduces brake fade. For daily drivers, they are mostly an aesthetic upgrade, but for spirited canyon driving or track days, the extra heat dissipation helps.

Can I install performance rotors on stock calipers?

Yes, as long as you buy stock-size replacement rotors designed for your specific car model year. Upgraded rotor materials and drill patterns fit standard factory calipers without needing custom brackets or lines.

How long do performance brake rotors usually last?

Most quality rotors last between 30,000 and 70,000 miles depending on your driving style and pad compound. Aggressive friction materials and track use will wear drilled surfaces down faster than normal highway cruising.

What happens if I miss the 18-month 0% APR deadline?

Any remaining balance starts accruing standard interest rates immediately after the 18 months end. Set up auto-pays for at least $50.00 per month right away so the balance drops to zero automatically before that window closes.